What Does Homeowners Insurance Cover in Florida?
Owning a home in Florida comes with unique responsibilities, especially when it comes to protecting your property from hurricanes, storms, and unexpected damage. Understanding what homeowners insurance covers in Florida can help you make informed decisions and avoid costly surprises.
Homeowners insurance generally protects your home, personal belongings, and certain personal liability risks. However, not every type of damage is covered, and some situations require additional insurance.
Knowing what your policy includes and excludes is an important step toward protecting your home and financial future.
What Is Homeowners Insurance in Florida?
Homeowners insurance is designed to provide financial protection when your home or belongings are damaged by covered events. It can also help with certain legal expenses if someone is injured on your property and you are found legally responsible.
In Florida, homeowners face risks such as hurricanes, strong winds, lightning, and heavy rainfall. Having appropriate coverage can help reduce the financial impact of unexpected events.
Most standard homeowners insurance policies include several important types of protection.
What Does Homeowners Insurance Cover in Florida?
1. Dwelling Coverage
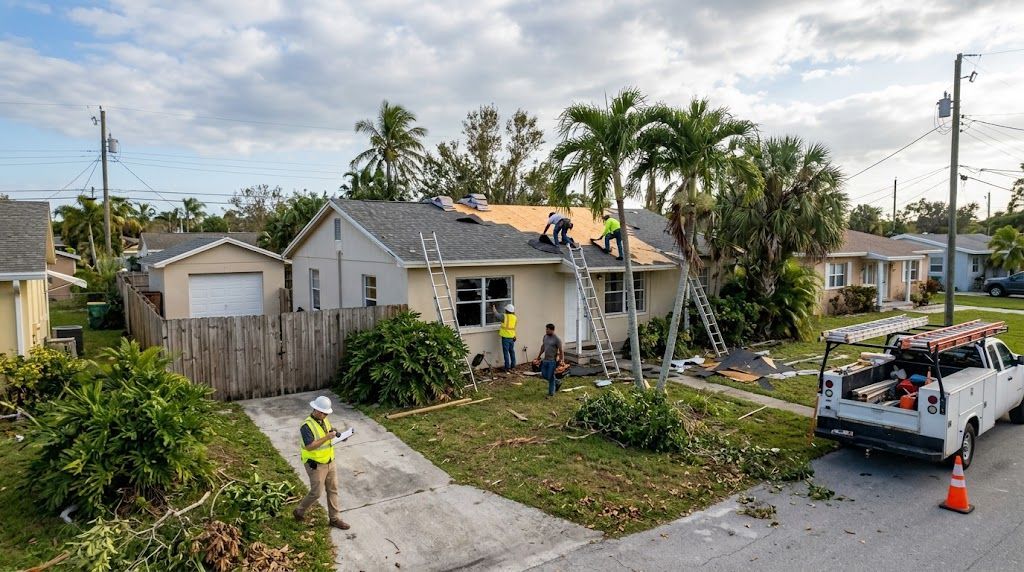
Dwelling coverage helps pay to repair or rebuild your home when it is damaged by a covered event.
Depending on your policy, covered situations may include:
- Fire and smoke damage
- Lightning strikes
- Windstorm damage, including hurricane-related wind damage
- Vandalism
- Certain types of accidental water damage
Coverage depends on your policy's terms, limits, deductibles, and exclusions. Hurricane-related claims may also have a separate deductible.
2. Personal Property Coverage
Personal property coverage helps protect belongings inside your home, including furniture, clothing, electronics, and appliances.
For example, if a covered fire damages your furniture and electronics, your insurance may help pay for replacement or repair.
However, expensive items such as jewelry, collectibles, and valuable artwork may have special coverage limits.
Reviewing your policy can help you determine whether additional protection is needed.
3. Personal Liability Protection
Personal liability coverage may help protect you financially if you are held legally responsible for someone else's injuries or property damage.
For example, if a visitor slips and falls on your property and you are found liable, your policy may help cover eligible medical costs, legal expenses, or settlements.
Coverage is subject to policy limits and exclusions.
4. Additional Living Expenses
If a covered event makes your home temporarily uninhabitable, your homeowners insurance may help pay for additional living expenses.
Eligible expenses may include:
- Temporary hotel accommodations
- Additional meal expenses
- Certain laundry costs
- Other necessary expenses above your normal living costs
This coverage can help your family maintain a reasonable standard of living while your home is being repaired.
Does Florida Homeowners Insurance Cover Hurricane Damage?
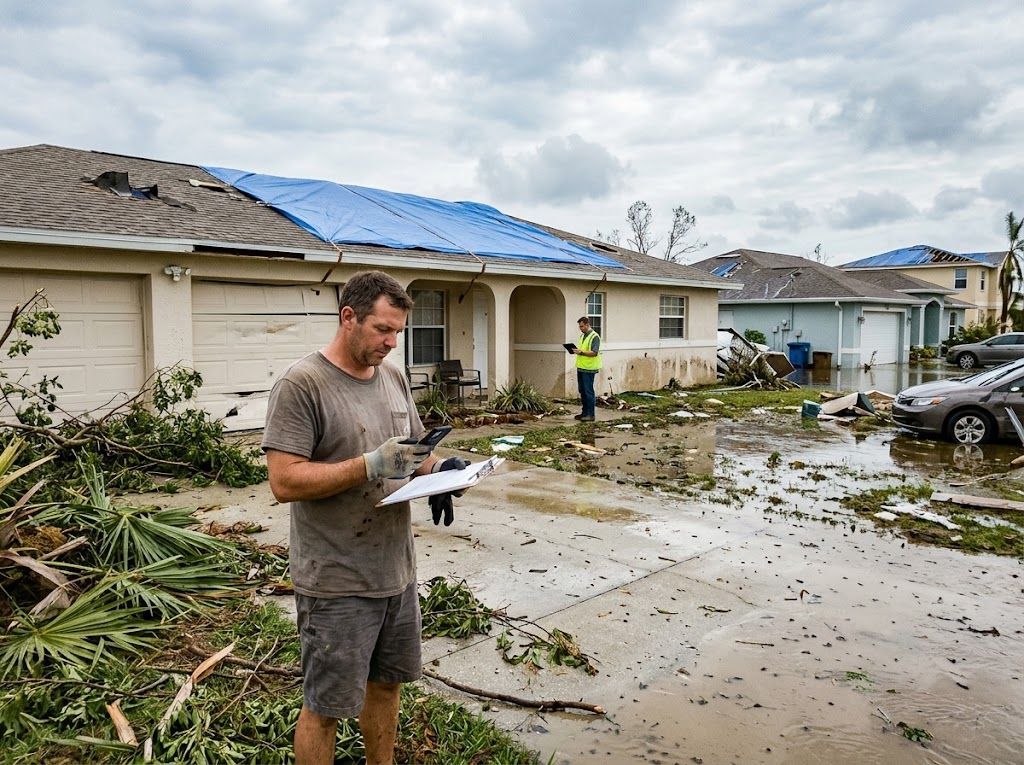
Hurricanes are among the biggest concerns for Florida homeowners.
Most standard homeowners insurance policies cover wind damage caused by hurricanes, subject to policy exclusions and deductibles. However, damage caused by flooding or storm surge is generally not included.
For example, if hurricane winds damage your roof, your homeowners policy may provide coverage. But if storm surge floods your living room, a separate flood insurance policy would generally be necessary.
Florida homeowners should understand their hurricane deductibles, windstorm coverage, and flood insurance options before hurricane season begins.
What Does Homeowners Insurance Not Cover in Florida?
Although homeowners insurance provides important protection, certain situations are commonly excluded.
These may include:
- Flooding: Flood damage usually requires separate flood insurance.
- Normal wear and tear: Damage caused by aging materials or poor maintenance is generally excluded.
- Pest damage: Damage caused by termites, rodents, or other infestations is typically not covered.
- Earth movement: Earthquakes and certain ground movement events may require separate coverage.
- Preventable maintenance problems: Damage resulting from long-term neglect or unresolved maintenance issues may not qualify for coverage.
Because exclusions vary, reviewing your policy carefully is essential.
How Much Homeowners Insurance Coverage Do You Need?
The right amount of homeowners insurance depends on your property's replacement cost, personal belongings, liability exposure, and financial situation.
Consider these factors when reviewing your coverage:
- Home replacement cost: Estimate how much it would cost to rebuild your home at current construction prices.
- Personal belongings: Calculate the value of your furniture, appliances, electronics, and other possessions.
- Liability limits: Consider how much financial protection you may need if someone files a covered liability claim.
- Deductibles: Understand how much you would pay out of pocket before insurance benefits apply.
- Additional coverage: Determine whether flood insurance or other optional protections are necessary.
Remember that your home's market value and rebuilding cost are not necessarily the same.
Protect More Than Your Home With Other Insurance Options
Protecting your property is important, but your family's financial security and healthcare needs also deserve attention.
Steve Smith Insurance Florida offers insurance services that can help individuals and families explore additional protection options.
Life Insurance for Your Family's Financial Future
Life Insurance can help provide financial support to your beneficiaries after your death.
Depending on the policy, benefits may help your loved ones manage mortgage payments, daily expenses, outstanding debts, and other financial responsibilities.
Reviewing your life insurance options can help you choose coverage that fits your family's needs and long-term goals.
Medicare Insurance Plans for Healthcare Coverage
Healthcare costs can become a significant concern as you approach retirement.
Medicare Insurance Plans can help eligible individuals explore coverage options based on their healthcare needs and budget.
Understanding available Medicare options can help you compare benefits, potential out-of-pocket costs, and provider networks before making a decision.
Short-Term Health Insurance for Temporary Coverage
Unexpected changes in employment or health insurance eligibility can leave individuals searching for temporary medical coverage.
Short-Term Health Insurance may provide limited medical benefits during certain coverage gaps, subject to eligibility and applicable rules.
These plans generally do not provide the same comprehensive protections as Affordable Care Act-compliant health insurance. Reviewing exclusions, benefit limits, and preexisting-condition restrictions is important before enrolling.
Frequently Asked Questions About Florida Homeowners Insurance
Does homeowners insurance cover roof damage in Florida?
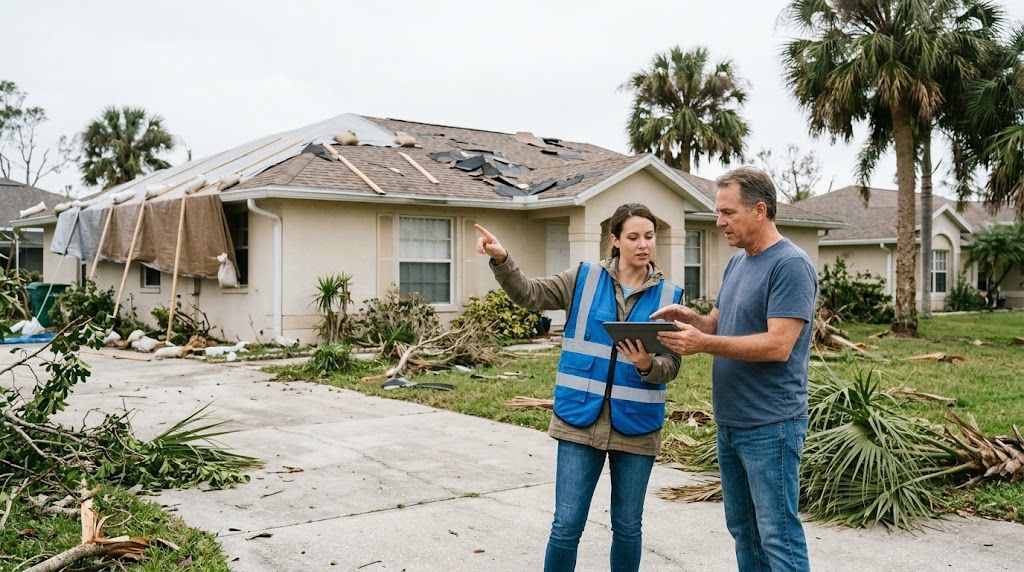
Homeowners insurance may cover roof damage caused by covered events such as hurricanes, windstorms, or falling objects. However, coverage depends on the cause of damage, roof condition, policy terms, and applicable deductibles.
Is flood insurance included in Florida homeowners insurance?
No. Standard homeowners insurance generally excludes flood damage. Homeowners typically need a separate flood insurance policy for protection against covered flooding.
Does homeowners insurance cover water leaks?
Some policies cover sudden and accidental water damage, such as damage from a burst pipe. However, gradual leaks, maintenance-related problems, and flooding may be excluded.
Is homeowners insurance required in Florida?
Florida law generally does not require homeowners to purchase homeowners insurance. However, mortgage lenders typically require insurance as a condition of the loan.
How often should I review my insurance coverage?
Reviewing your insurance coverage at least once a year is a good practice. You should also review your policy after major renovations, significant purchases, or changes in your household's financial needs.
Schedule an Insurance Consultation With Steve Smith Insurance Florida
Understanding what homeowners insurance covers in Florida is an important part of protecting your property. It is equally important to consider how other insurance products can support your family's financial and healthcare needs.
Ready to review your insurance needs? Contact Steve Smith Insurance Florida to schedule a consultation and learn more about available coverage options.
Phone: (865) 803-3045
Email: stevemedicarefix@gmail.com
Website: www.stevesmithinsuranceflorida.com
Schedule your insurance consultation today and take the next step toward protecting what matters most.
*This content is developed from sources believed to be providing accurate information. The information provided is not written or intended as tax or legal advice and may not be relied on for purposes of avoiding any Federal tax penalties. Individuals are encouraged to seek advice from their own tax or legal counsel. Individuals involved in the estate planning process should work with an estate planning team, including their own personal legal or tax counsel. Neither the information presented nor any opinion expressed constitutes a representation by us of a specific investment or the purchase or sale of any securities. Asset allocation and diversification do not ensure a profit or protect against loss in declining markets. This material was developed and produced by Advisor Websites to provide information on a topic that may be of interest. Copyright 2021 Advisor Websites.